Abstract:India's capital markets regulator has aligned the exchange-traded rupee currency derivatives market with the central bank's revised rules, capping positions taken without proof of underlying foreign exchange exposure at a single $5 million limit. According to Moneycontrol, the Securities and Exchange Board of India (SEBI) issued the change in a circular on Thursday, following the Reserve Bank of India's (RBI) October 10 decision to lower the threshold for such transactions.
India's capital markets regulator has aligned the exchange-traded rupee currency derivatives market with the central bank's revised rules, capping positions taken without proof of underlying foreign exchange exposure at a single $5 million limit. According to Moneycontrol, the Securities and Exchange Board of India (SEBI) issued the change in a circular on Thursday, following the Reserve Bank of India's (RBI) October 10 decision to lower the threshold for such transactions.
For readers new to forex, a currency derivative is a contract whose value moves with an exchange rate. An underlying exposure is a real foreign currency obligation, such as an import bill, an export receipt or an overseas investment, that the contract is meant to protect against. Positions taken without that proof are often described as unhedged, meaning the investor is carrying currency risk rather than offsetting an existing one.
 Contents
One Ceiling Across Pairs and Exchanges
Under the revised framework, domestic investors and foreign portfolio investors (FPIs, overseas funds that invest in Indian securities) can take long or short positions of up to $5 million in currency derivatives involving the Indian rupee without having to demonstrate an underlying foreign exchange exposure. A long position broadly gains if the rupee strengthens against the other currency, while a short position broadly gains if it weakens.
The key change is how that figure is counted. The $5 million limit applies to the combined outstanding notional value of positions across all currency pairs involving the rupee and across all recognised stock exchanges. Notional value is the face value written into a contract rather than the amount actually paid upfront. In practice, investors cannot claim a separate $5 million allowance for each currency pair or each exchange; the ceiling is one pool, measured on the notional value outstanding at any point in time.
The revision follows the RBI's October 10 decision to reduce the threshold for undertaking foreign exchange derivative transactions without establishing underlying exposure to $5 million. SEBI's circular brings the exchange-traded segment into line with that central bank circular, so the rules governing positions on recognised exchanges now mirror the broader framework for rupee foreign exchange derivatives.
Separate Conditions for FPIs and Domestic Clients
SEBI set out distinct conditions for investors who want to go beyond the threshold. FPIs must ensure that their aggregate short positions across all stock exchanges in foreign currency-rupee pairs do not exceed $5 million. For long positions above $5 million, FPIs must establish underlying exposure in Indian debt or equity securities, including units of equity and debt mutual funds.
Domestic investors can take positions exceeding $5 million but must provide supporting documentation. They must also give an undertaking that the same underlying exposure has not been hedged through another authorised dealer, which is a bank or entity permitted to deal in foreign exchange. Where the exposure is hedged through multiple dealers, the amounts booked with each dealer must be disclosed.
For domestic clients, the conditions for positions beyond the limit are those specified by the RBI in its master direction on Risk Management and Inter-Bank Dealings dated October 10. That places the detailed eligibility and documentation requirements with the central bank, while SEBI's circular governs how they apply on recognised exchanges.
Rebooking Ban and Implementation Duties
The RBI has also tightened the rules on cancellation and rebooking of foreign exchange derivative contracts. Contracts cancelled after October 10, 2026 cannot be rebooked, although rollover of contracts on maturity is permitted subject to applicable conditions. Rebooking refers to entering a new contract after cancelling an earlier one, a practice the revised rules now restrict for cancellations after that date.
SEBI has asked stock exchanges and clearing corporations to put systems in place to implement the revised provisions and to make consequential amendments to their rules and regulations. Clearing corporations stand between buyers and sellers and guarantee settlement, so their systems determine how the combined limit is tracked across contracts and venues.
The changes matter for anyone using exchange-traded rupee derivatives, from companies hedging import or export payments to funds taking a view on the currency. Because the $5 million allowance is now a single combined ceiling, an investor using several rupee pairs or trading on more than one exchange has to track total outstanding notional value rather than treat each position separately.
Follow WikiFX for the latest forex news and updates worldwide.
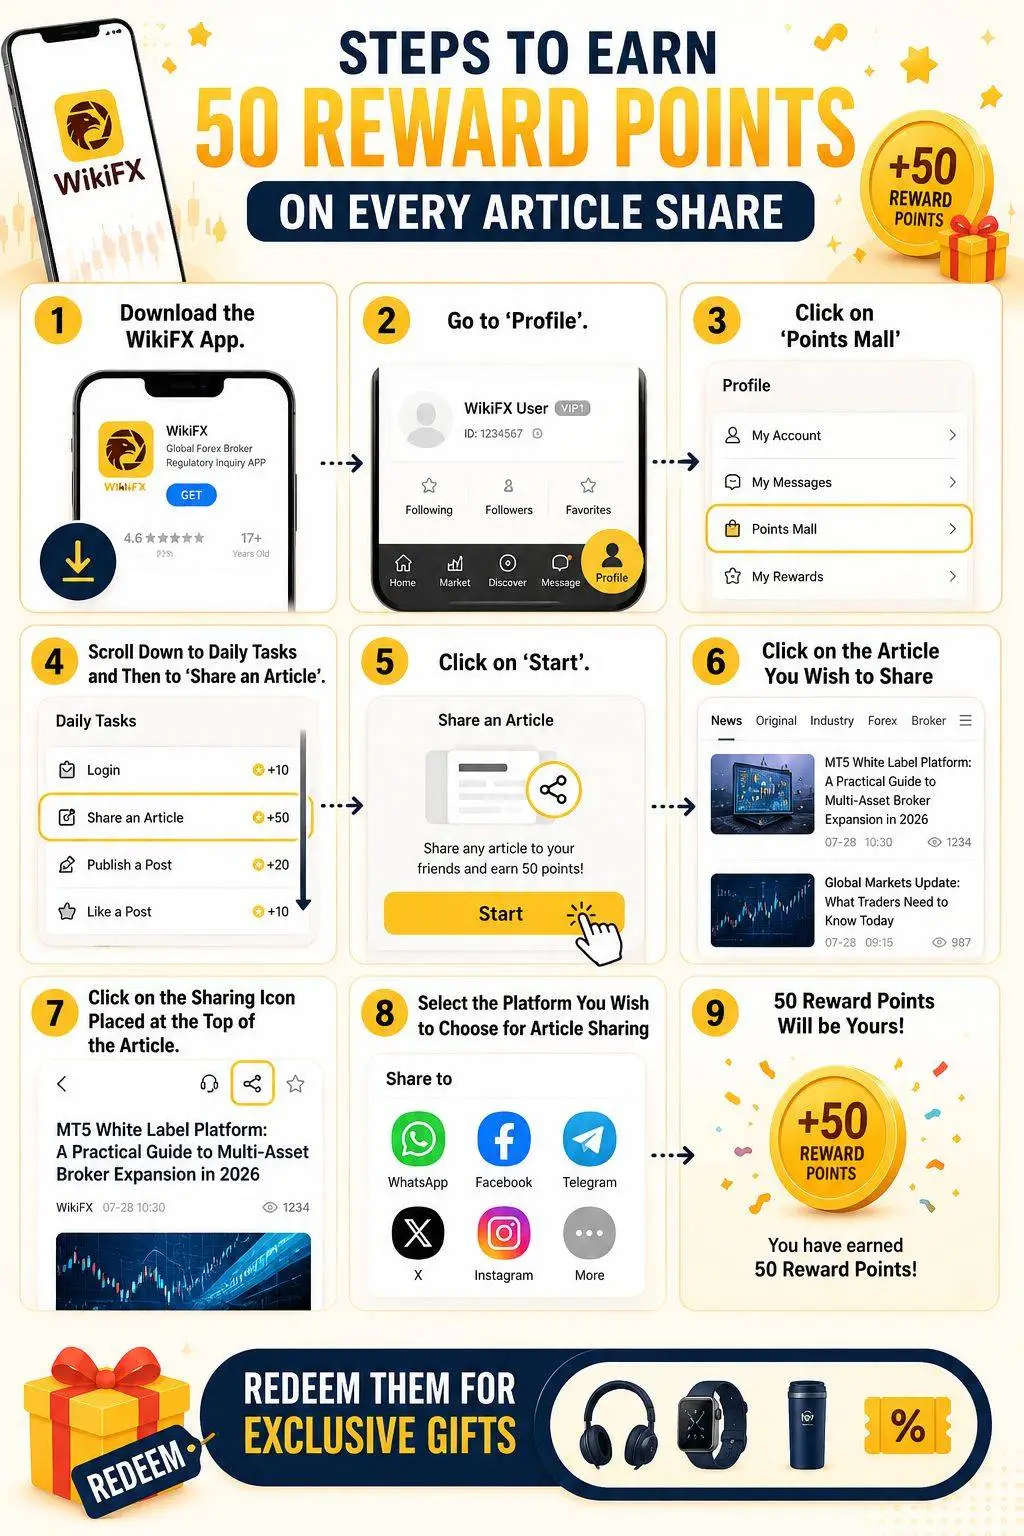
Knowledge pays at WikiFX.Every time you share a WikiFX article, you'll receive 50 Reward Points. Grow your rewards with every share and unlock exclusive gifts in the WikiFX Points Mall. Start earning today!