Abstract:Indian stocks have fallen for eight straight weeks. The economy grew 7.8% in the June quarter. In a post on flow problem, not a growth problem.
For anyone trading USD/INR, that distinction decides where the pressure lands. The rupee has been hovering around 96 per dollar, with the Reserve Bank of India selling dollars to keep the move orderly (Rediff MoneyWiz). Orderly spot is not the same thing as cheap carry. The cost of that stability shows up elsewhere.
Indian stocks have fallen for eight straight weeks. The economy grew 7.8% in the June quarter. In a post on flow problem, not a growth problem.
For anyone trading USD/INR, that distinction decides where the pressure lands. The rupee has been hovering around 96 per dollar, with the Reserve Bank of India selling dollars to keep the move orderly (Rediff MoneyWiz). Orderly spot is not the same thing as cheap carry. The cost of that stability shows up elsewhere.
 Contents
Eight Weeks of Losses, a 27-month Low, Rs 20 Lakh Crore Gone
On 29 September the Sensex broke below 72,100 for the first time since 4 June 2024, when it had touched 72,079.05. The intraday low that day was 72,064. By the end of the week the Sensex closed at 71,909.70, down 2.7%, and the Nifty settled 3.1% lower at 22,421.95 after touching an intraday 22,569.65, a six-month low.
Year to date the Sensex has shed 12,619.68 points, or 14.81%. The Nifty is down 3,430.35 points, or 13.12%. From its December 2025 record of 86,159.02, the Sensex has lost 16.4%; the Nifty is 14.4% below its 26,373.20 peak. Around Rs 20 lakh crore of market capitalization disappeared in 30 days. Forty of the Nifty's 50 stocks ended September lower.
The Sensex fell 5.8% in September, its second straight monthly drop, and the Nifty lost 6.1%, its worst month since March (Analytics Insight). This is the longest weekly losing run in 25 years (Goodreturns).
Foreign Money: $40 Billion Out in Two Years, and the Exit is Not Slowing
FIIs were net sellers for a seventh straight week at the end of September, offloading Rs 34,966 crore of equities. Domestic institutions bought Rs 33,455 crore in the same week and absorbed most of it.
In September alone, foreign investors sold USD 2.7 billion. Net selling for 2026 has reached USD 26.8 billion (Analytics Insight). NSDL and CDSL data cited by Outlook Money put 2026 sales at Rs 2,15,300.55 crore, with FIIs net sellers in five of the year's nine months. Almost $40 billion has left Indian equities since September 2024, the last month in which foreign monthly inflows topped $5 billion, according to a Bernstein note.
The annual tallies show the acceleration: Rs 3,02,434.91 crore sold in 2024, Rs 3,06,419.09 crore in 2025, and Rs 3,82,938.85 crore in under nine months of 2026, closing in on a first-ever Rs 4 lakh crore year.
Over a full decade, foreign funds have netted just $4 billion of Indian stock. Domestic institutions bought more than $300 billion over the same period. Bernstein's read is that the old assumption of India as an automatic portfolio destination has “fractured.” The same note points out that the Nifty has returned minus 6% annualized in dollar terms over ten years, and roughly minus 11% over the last two.
Bernstein on the composition problem: “Many of India's large caps represent a bygone economic era. Most are not investing in the future, but consolidating their past, often expecting policy to continue shielding them from global competition.”
Oil at $106, the US 10-year at 5.23%, a 13% Monsoon Shortfall
Brent has stayed near or above $100 in recent weeks. Geojit Investment Strategist VK Vijayakumar put it above $106 with the US 10-year yield at 5.23% in comments quoted by Goodreturns. “The emerging macro scenario in the US appears to be one of high growth and high inflation,” he said, adding that AI-driven spending keeps both elevated and warrants one more Fed hike.
India imports most of its crude. The chain runs like this: a bigger import bill widens the trade deficit, more dollars get bought, the rupee weakens, imported inflation rises. Vijayakumar's follow-on point is the one worth holding on to. Higher crude prices have not been passed on to consumers, so the fiscal strain lands on FY27 instead.
There is a domestic supply-side risk stacked on top. The southwest monsoon recorded a 13% shortfall, which raises the odds of persistent food inflation (Goodreturns). Sachin Gupta, VP of Research at Choice Broking, points to continued Middle East uncertainty keeping investors cautious.
Why the Rupee Sits at 96
Rediff MoneyWiz reported the rupee hovering around 96 with RBI intervention volatility limiting. The currency slipped past 96 in September and is close to its May record low of 96.96 (Analytics Insight).
Here is the part that does not show up in a spot quote. When the RBI sells dollars in the spot market, it absorbs rupee liquidity, and the adjustment typically surfaces in forward premia rather than in the spot rate. For a trader holding USD/INR overnight, that is a rollover cost, not a headline number. Spot stability near 96 therefore says very little about what it costs to stay positioned.
The rate side matters just as much. The RBI has held the repo rate at 5.25% for four straight meetings. Retail inflation hit 4.82% in August, the highest since December 2024, and the central bank expects prices to peak in the October to December quarter. ICRA has flagged the risk of a hike before December. In August the RBI raised its growth forecast for the year ending March 2027 to 6.7%.
Where the Reports Do Not Line Up
The September Nifty number differs by comparison base. Analytics Insight records a 6.1% fall, the worst month since March. ET Now records the worst September since 2018, with a 4% drop over two weeks. Both can be right, and neither is a forecast.
FII totals are quoted in different windows and currencies. Outlook Money cites Rs 2,15,300.55 crore sold in 2026 to date. Analytics Insight gives USD 26.8 billion for the same year. Good returns cites Rs 3,82,938.85 crore for under nine months, and separately over $40 billion of exits across two years. These are not interchangeable numbers, and no single window explains the others.
Sensex levels also move with the timestamp. Analytics Insight has the index closing at 72,480.29 on 30 September. Goodreturns has the week closing at 71,909.70. Both are in the same week.
On cause, the split is genuine. Bernstein argues the historical link between real GDP growth and foreign flows has weakened and turned negative in recent cycles, and that the Fed-RBI rate differential stopped driving allocations after 2018. Against that, Edelweiss Mutual Fund's Radhika Gupta has said higher small- and mid-cap valuations are justified, while expecting volatility from crude, bond yields and FII outflows (The Financial Express). That is the only pushback in the batch against the “expensive valuations” item on Goenka's list.
What Traders on X are Arguing About
Seven posts reviewed here share one premise and split on another. The common ground is that something has broken between India's growth and its market. @harshmadhusudan, who says he has followed global markets for two decades, writes that he has “rarely seen such despondence about the India story.”
The split is over the cause. @TheNavroopSingh puts it on fundamentals: slower nominal GDP growth, high taxes on FIIs, no AI play. @aakankshalovely frames it historically, noting that India led the IT revolution from 2000 to 2025 and that the resulting dollar inflows made the economy resilient, which implies the model needs a successor. @rajuidesai points entirely outward, citing US government overspending of $1.8 trillion to $2.0 trillion a year.
Two posts are on RBI watch. @SharePurana says rate-hike conditions “are starting to look uncomfortable.” @TWS_EDUCATES states that the October MPC meeting “has started,” with the repo rate at 5.25%. That claim is not confirmed by any report reviewed here, and the reported decision date is 7 October. @ViveKSingh_DC calls the whole thing a political distraction and offers no market thesis.
Two things worth noting. No post reviewed here cites an FX level, a forward premium or a carry cost. And the seven items on Goenka's list each appear in the reporting above, but no media outlet reviewed here reproduces his list as analysis. It is one investor's framing, not a consensus.
What Determines the Rupee's Next Move
Three checkable items, in order.
First, 7 October. The RBI's rate decision. The repo rate sits at 5.25%, August CPI printed at 4.82%, the RBI expects the inflation peak in the October to December quarter, and ICRA has flagged a possible hike before December. A hike widens the rate gap in the rupee's favor. Holding the rate changes nothing about carry.
Second, Q2 earnings. TCS reports first, with HCL Tech and Infosys behind it. The Nifty IT index fell more than 11% in September. Kotak expects TCS revenue to grow 2.8% year on year, with weak revenue offsetting the weaker-rupee benefit. Market estimates for profit growth have slipped to 13% to 14% from 18% to 19% in the first quarter.
Third, the two external numbers feeding the USD/INR story. The US 10-year at 5.23% and Brent above $100. If yields keep climbing while the RBI caps spot, the adjustment keeps landing in forward points rather than in the quoted rate, which raises the cost of holding a long USD/INR position overnight. If crude stays above $100, the import bill and the rupee's floor both come under strain. The May record low of 96.96 is the level the market has already tested once.
Watch the RBI's spot behavior around 96, and watch DII flows. Their Rs 33,455 crore of weekly buying is what has kept the index from falling faster. Foreign flows, not domestic buying, set the rupee's direction.
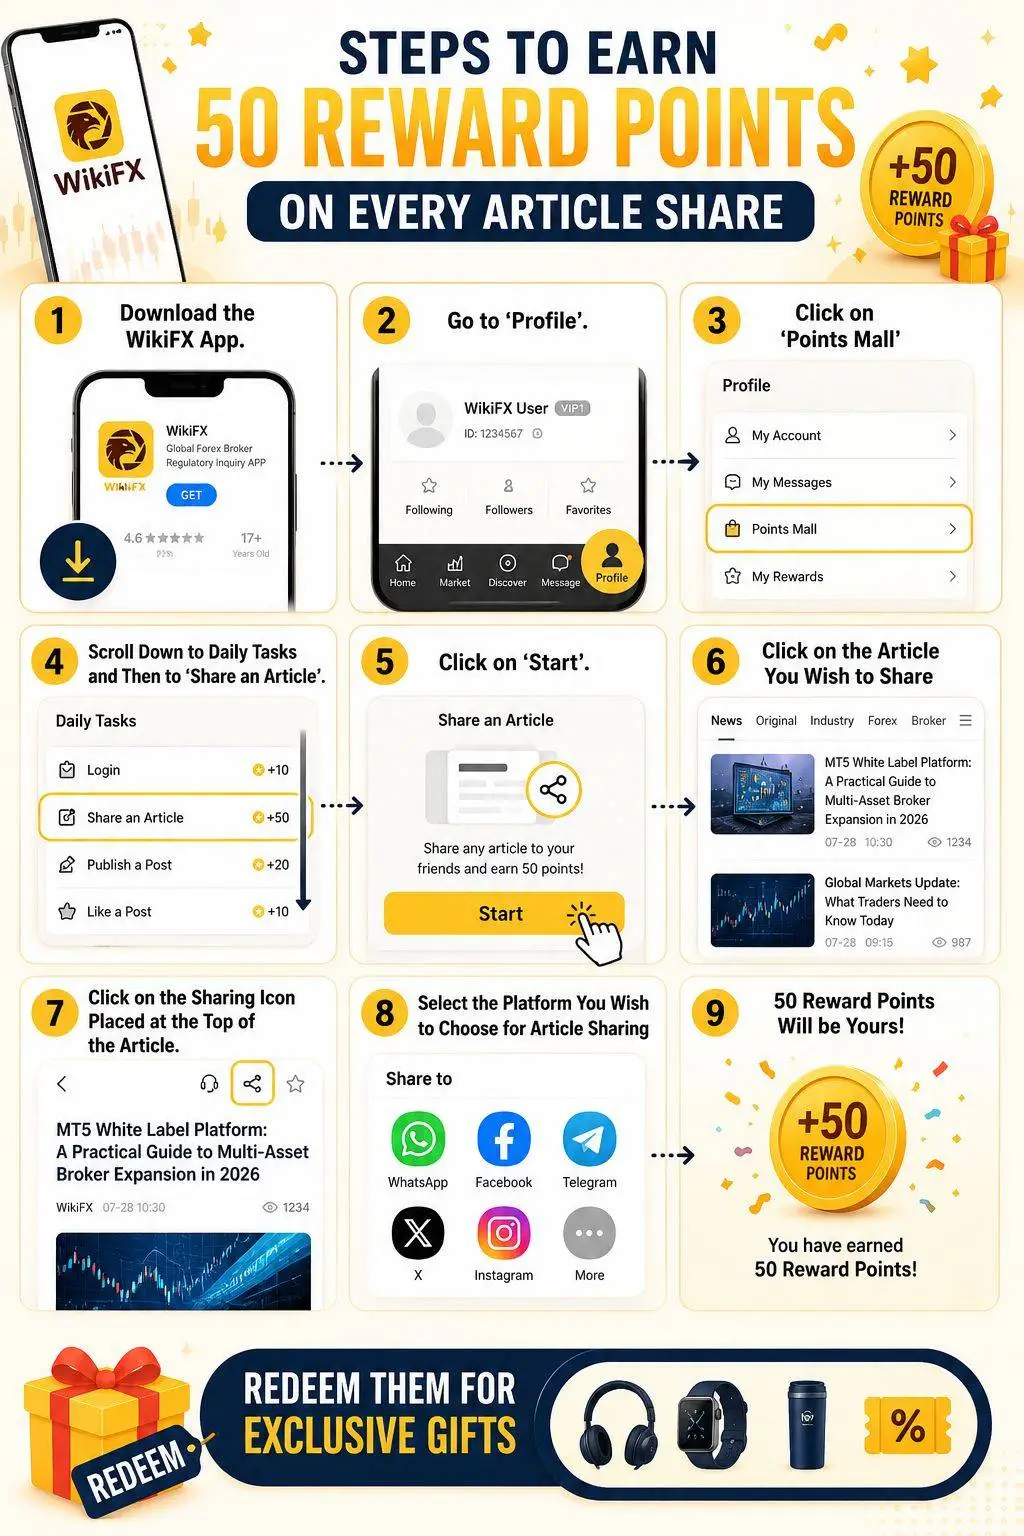
Download the WikiFX app for the latest financial news and insights.
Knowledge pays at WikiFX.Every time you share a WikiFX article, you'll receive 50 Reward Points. Grow your rewards with every share and unlock exclusive gifts in the WikiFX Points Mall. Start earning today!